Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
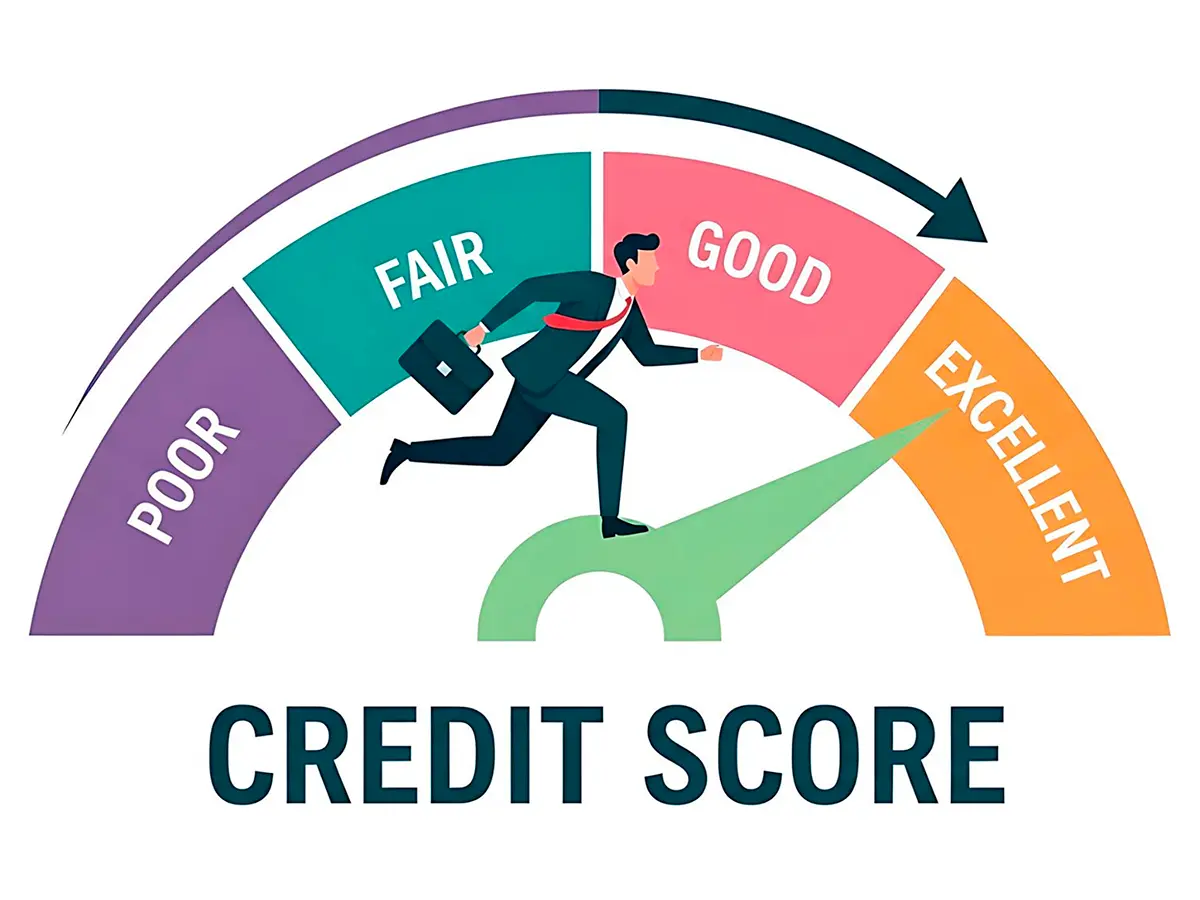
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair services near me: a practical selection guide
What "near me" should really deliver
Local help should mean faster context, live accountability, and clearer next steps. A nearby provider can explain state-specific collection laws, meet face to face, and coordinate documents without endless email chains. Proximity is useful - but fit, safety, and measurable progress matter more.
Safety first: nonnegotiables
- No advance fees: legitimate firms bill only after work is performed; avoid anyone demanding payment upfront.
- Written contract: you receive a plain-language agreement with services, timelines, and your 3-day right to cancel.
- Realistic claims: no promises of a "clean slate," new identities, or guaranteed deletions.
- Privacy discipline: secure document handling; no sharing of your data without consent.
- Transparent methods: they dispute inaccuracies under FCRA, not shotgun-mail vague letters.
- Local legitimacy: check business registration, complaints with your state attorney general, and patterns in reviews - especially how issues were resolved.
- Clear billing: itemized work logs, no surprise add-ons, easy cancellation.
A simple selection framework
- Define your target: remove inaccurate negatives, correct personal data, and build positive trade lines over time.
- Inventory reports: pull Experian, Equifax, and TransUnion; mark each questionable item with why it may violate accuracy, completeness, or verifiability.
- Shortlist three options: one nonprofit counselor, one attorney-led practice, one established specialty firm near you.
- Verify compliance: ask how they bill post-service, deliver contracts, and protect data.
- Interview quickly: "What will you do in the first 30 days? How do you escalate creditor errors? What's a typical timeline for medical or student loan disputes?"
- Compare value: price per month vs. scope (disputes, goodwill requests, validation letters, education, score tracking).
- Pilot one month: select the best fit, set expectations in writing, and schedule a 15-minute weekly check-in.
Pause - slow decisions beat rushed commitments.
Signals of quality you can spot
- They start with education: how credit scoring treats utilization, age, mix, and inquiries.
- They prioritize accuracy: dispute only items with a concrete basis, customized to each bureau.
- They measure progress: monthly side-by-side updates and documented challenges sent.
- They guide behavior change: plan to lower utilization and add on-time history, not just delete negatives.
Who does what (so results stick)
- Provider: craft precise disputes, validate debts with collectors, escalate to furnishers, correct personal data, and coach next steps.
- You: pay on time, trim card balances below 30% (ideally 10%) of limits, avoid new hard inquiries, set fraud alerts or freezes if needed, and save every letter received.
Cost clarity
Expect transparent month-to-month pricing (often $50 - $150 after work is done). Attorney involvement may bill hourly for complex errors. Nonprofits may be free or low-cost and can be a strong first stop if budget is tight.
A quick real-world moment
Last month, I sat in a neighborhood library conference room with a resident who searched "credit repair services near me," then booked a 20-minute consult with a nearby nonprofit. Three targeted disputes corrected a mixed-file error, and her score recovered 48 points in six weeks - no gimmicks, just accurate reports and lower utilization.
Take action today
- Pull all three reports and highlight questionable items with reasons.
- Call two local providers and one nonprofit; ask the three interview questions above.
- Select a one-month pilot, set a weekly check-in, and document every step.
- Automate payments and reduce one balance before the next statement date.
Local can be powerful - so long as it is compliant, transparent, and focused on verifiable results. Start small, move fast, and protect yourself at every step.
But how can one enjoy this Louisville spirit with a credit score that hinders you? That's where WJA comes in. CREDIT REPAIR SERVICES IN LOUISVILLE, KY. You may ...
All "Credit Repair Service" results near me in Lexington, Kentucky - February 2025. Showing 1-16 of 17 - Works of Art Clock Sales & Repair. 1. - Restarting ...
ME. RI. NY. PA. NJ. DE. MD. VA. WV. OH. IN. IL. CT. WI. NC.
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.